Watch This Lesson
The binder is the problem.
You do the hard work, make the hard decisions, sign in front of witnesses, and someone hands you a bound folder with your name on the spine. It feels finished. It goes in the safe, and estate planning comes off the list permanently.
When we set these documents up, when we create this package, it’s based on the snapshot of how our life was at the time. What our assets were, who our beneficiaries were going to be, what our wishes were at that time. But as life progresses, our beneficiaries get older, our assets change. Life is always changing. And so as it changes, so do our documents need to change.
A plan is a photograph of one afternoon. Your life keeps running after the shutter closes. Ten years on, a document that was exactly right can describe a family that no longer exists and assets you no longer own.
What Pulls a Plan Out of Date
People. Births, marriages, divorces, deaths, estrangements.
Life will give us lots of reasons to do that. People get married, divorced, babies are born… We choose different institutions or charities that we want to donate to. There are a lot of reasons why updating your trust or your will makes sense. But often I see that people just don’t do it. It’s not top of mind.
The dangerous version of this is not a new grandchild — most plans handle that with class language covering descendants. It is the fiduciary who is no longer able. Your named executor is now 84 and in memory care. Your trustee died last year. If the successor list has run out, your estate needs a court to appoint someone, which is the exact outcome the plan was built to avoid. Check the people, not just the percentages.
Property. New accounts, a business interest, an inheritance, and above all real estate.
This is where trust-based plans quietly fail. A trust only controls what it owns. Buy a condo in another state, take title in your own name, never deed it to the trust, and that one property goes through probate — in that state’s courts, under that state’s rules, with a lawyer licensed there. It is called ancillary probate, and it is the most common way a fully paid-for trust ends up accomplishing nothing for a significant asset.
Every time you buy real property or open an account, the follow-up question is: does this need to be titled in the trust, or does it need a beneficiary designation? Ask it at the closing table, not years later.
Law. Statutes change underneath a plan that has not moved.
The clearest recent example is inherited retirement accounts. The SECURE Act and SECURE 2.0 replaced the old lifetime stretch approach with a ten-year distribution requirement for most non-spouse beneficiaries. Trusts drafted to receive IRA assets under the old rules can now produce compressed, heavily taxed distributions — sometimes taxed inside the trust at trust rates. If your plan names a trust as beneficiary of a traditional IRA or 401(k) and was drafted before these changes, that is a specific question to bring to your attorney and your CPA together. Exemption amounts also move with inflation and with legislation, so thresholds a plan was built around may no longer be the thresholds that apply.
The Five-Minute Habit
Renee’s method for staying current is the most practical thing in this lesson, and it costs nothing.
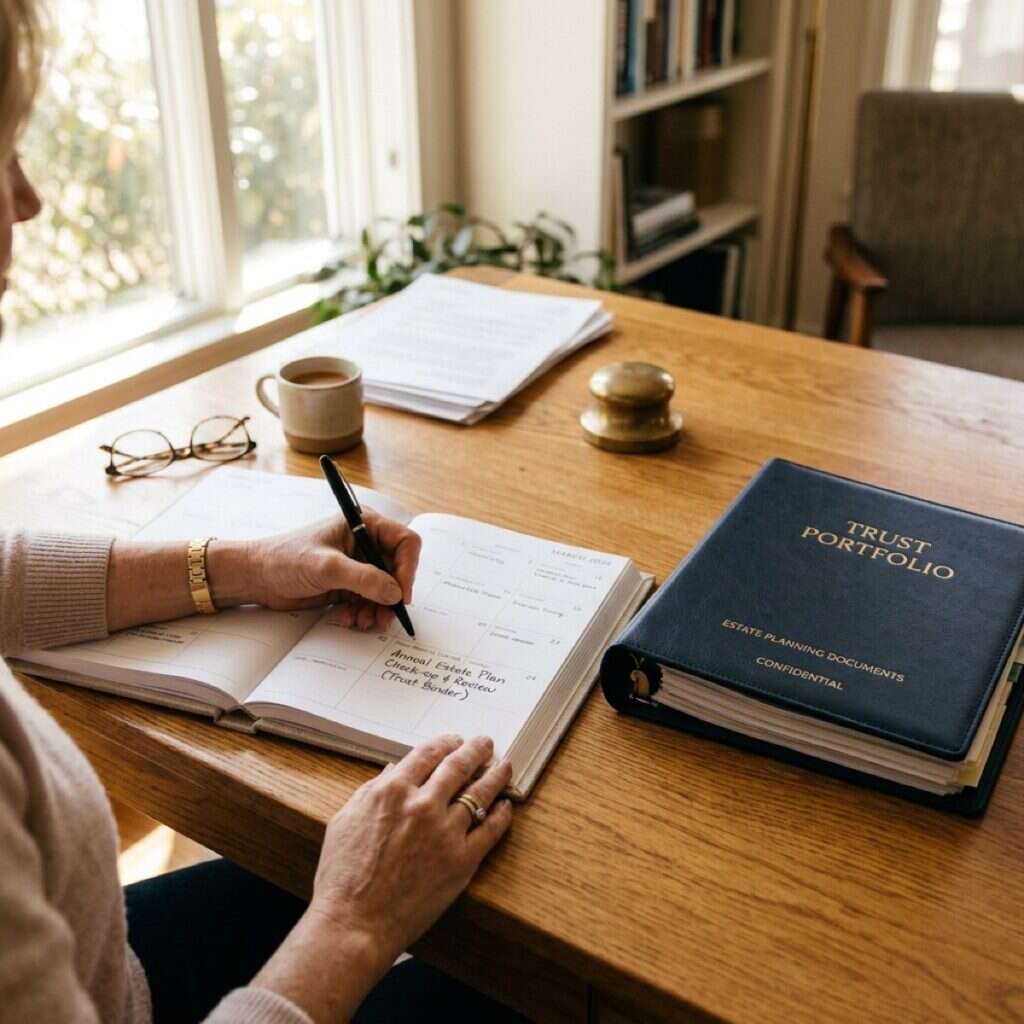
Here’s a general rule of thumb to help keep you on track with that. Whatever month your will was created or your trust was established, let’s say it’s the month of March. Every March, just put a little reminder to yourself to sit down and take five minutes to think about my estate planning documents. Has anything happened in the last 12 months that require me or suggest to me that I need to update my documents? Maybe somebody moved. Maybe, like I said, a new grandbaby was born. Maybe you want to change the percentages or the amounts… So whatever the situation is, take the five minutes, make some decisions about what needs to be updated, and then have those documents updated so they’re as relevant as can be.
Find the execution date on your documents. Put a recurring annual reminder in that month. That is the whole system.
What makes it work is that it is tied to a date rather than to a feeling of being overdue. Nobody wakes up thinking their trust needs attention. Everyone responds to a calendar entry.
“I Cannot Afford to Redo This Every Year”
That is the objection, and it rests on a false assumption. An annual review is not an annual redraft.
Most years the answer is nothing has changed, and the review costs you five minutes and nothing else. When something has changed, the usual fix is an amendment to a trust or a codicil to a will — a narrow document addressing the specific change, at a fraction of the original cost. A full restatement is for plans that have drifted badly over many years, which is precisely what reviewing annually prevents.
The expensive path is the other one: ten years of no review, then a complete rebuild, or worse, no rebuild and your family discovers the gap after you are gone.
Your Annual Five Minutes
Keep this list with the documents and run it once a year:
- Are the people still right? Executor, trustee, successors, agents under both powers of attorney, guardians. Alive, able, willing, and still the ones you would choose.
- Did anyone enter or leave the family? Birth, marriage, divorce, death, estrangement.
- Did I buy real estate? If yes, is it titled correctly? Property in another state is the urgent case.
- Did I open, close, or roll over any account? Check that each one has a current primary and contingent beneficiary, or is properly titled in the trust.
- Has it been more than three years since I signed my powers of attorney? Re-execute them even if nothing changed. Facilities reject documents they consider stale.
- Do the people who need these documents know where they are and how to get them?
Six questions, once a year, in the month you signed. If every answer is clean, close the binder and go about your day. If one is not, call your attorney while it is still a small amendment.
Your plan does not need to be perfect forever. It needs to still be true.
This article is for educational purposes only and does not constitute legal, tax, or financial advice. Trust amendment and will revision requirements, ancillary probate procedures, and the treatment of inherited retirement accounts vary by state and by individual circumstances, and federal retirement and estate tax rules continue to change. Consult a licensed estate planning attorney and a certified public accountant in your state before amending any document or changing how an asset is titled.
About the instructor: Renee Parris is an estate planning educator with over 30 years of experience. This article is a companion piece to Renee’s course, Estate Planning, Simplified.